SPACs now account for 60% of all U.S. IPOs, with 363 active vehicles holding $57.6 billion in trust and 109 live deals worth $71.8 billion. Our monthly read on macro, markets and the de-SPAC backlog.
Originally published on Welsbach SPACtacular Insights (Substack)
We spend hours researching and talking to the smartest founders, dealmakers and investors in the SPAC landscape. This is our attempt to give you a short summary of how we are thinking about the macro, markets and SPACs, and what lies ahead.
Quick Macro TL;DR
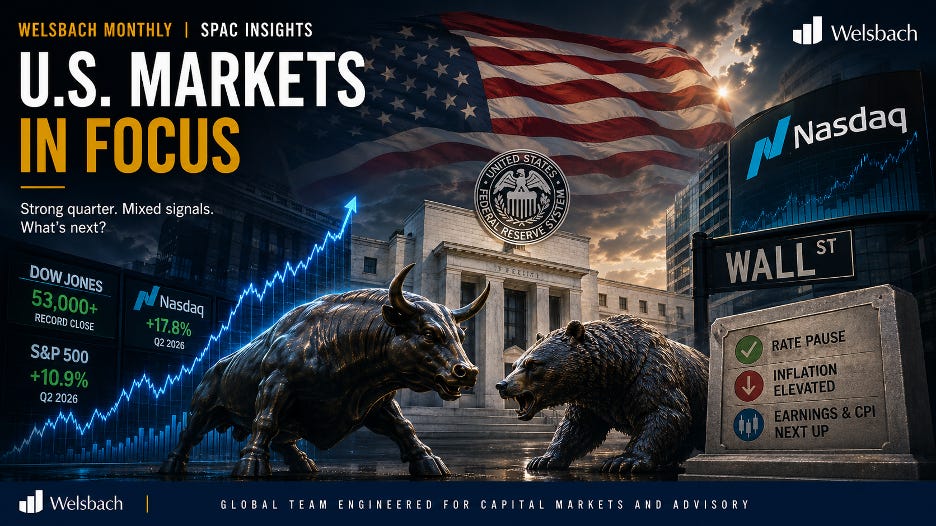
U.S. equities finished the period near record highs, recovering from the early-June selloff as easing Middle East tensions pushed oil sharply lower and improved investor sentiment.
The June 17 FOMC kept rates unchanged but adopted a more hawkish stance, lifting rate expectations for 2026. A weaker-than-expected July payrolls report, coupled with downward revisions to prior months, then reduced expectations of a near-term rate hike.
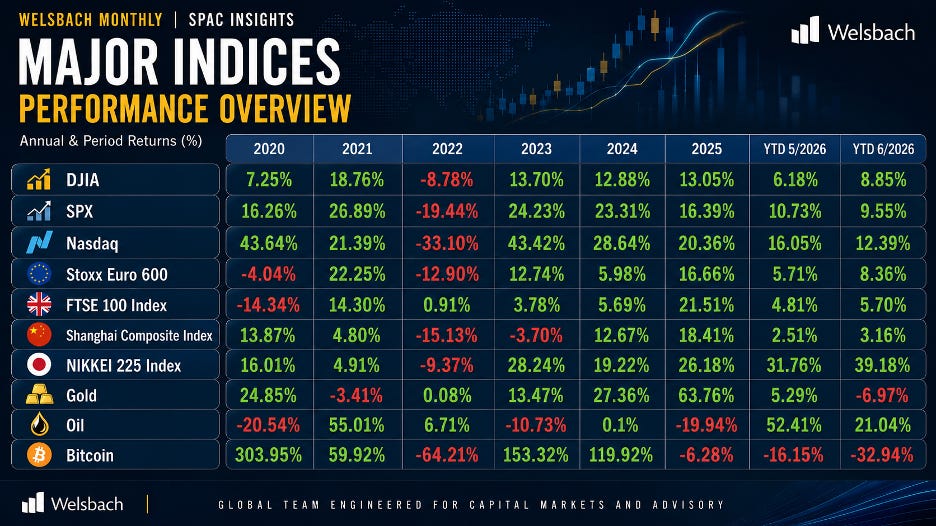
The Dow closed above 53,000 for the first time, capping the strongest quarterly performance for U.S. equities since 2020, although a late-June semiconductor pullback left the Nasdaq below its peak. Attention now turns to the July CPI release, Q2 earnings season and the July FOMC meeting.
The Good
- The U.S.-Iran framework ended the oil shock and the single largest driver of the inflation surge. The June 14 ceasefire extension and reopening of the Strait of Hormuz sent oil prices to three-month lows, giving the Fed greater flexibility to keep rates on hold.
- Best quarter since 2020, a Dow record above 53,000 and a broadening rally. The S&P 500, Nasdaq and Dow all posted double-digit gains, while leadership broadened beyond mega-cap technology, with small caps delivering their best first half since 1991.
- Soft June payrolls took near-term rate hikes off the table, pushing Treasury yields and the U.S. dollar lower. Markets read the softer labor data as supportive for risk assets rather than a sign of slowing growth.
- The IPO window is wide open. SpaceX raised $85.7 billion in the largest listing in history, and record first-half activity on Nasdaq reinforced confidence that the equity capital markets recovery remains firmly intact.
The Bad
- Inflation is running at multi-year highs and it is no longer just energy. May CPI rose to a three-year high and core PCE reached its highest level since late 2023.
- The Warsh Fed delivered the most hawkish pivot in years and abolished forward guidance, pushing Treasury yields higher and increasing market sensitivity to incoming data.
- Beneath the payroll headline, labor demand and the consumer are cooling, with participation declining and employment weakening across several consumer-facing sectors.
- The semiconductor correction stress-tested the AI trade and exposed concentration risk, highlighting the market's continued reliance on a narrow group of mega-cap technology companies.
SPAC Share of U.S. Listings Nears 2021 Record as De-SPAC Backlog Swells
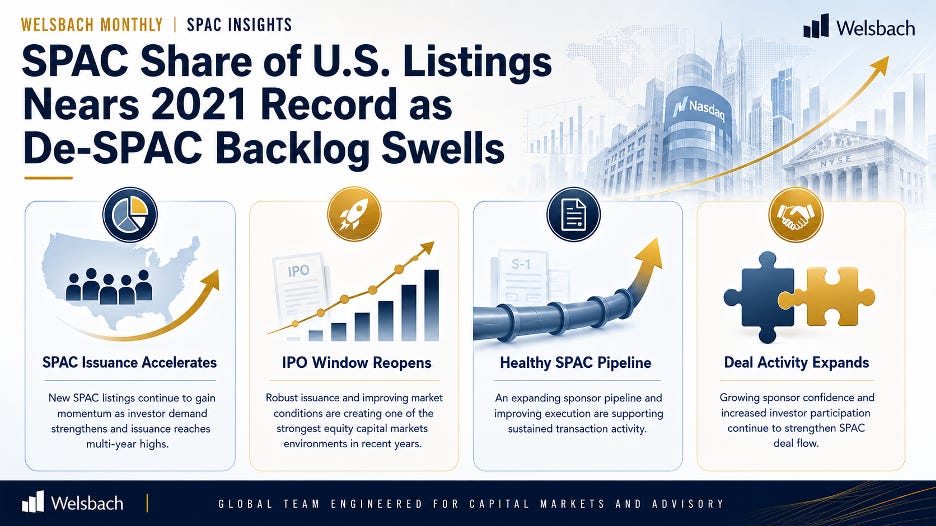
- SPACs represented 60% of all U.S. IPOs in H1 2026, just below the 61% peak in 2021, up from 42% in 2025 and the 19% low in 2024. June recorded 19 SPAC IPOs versus 16 traditional IPOs, the fourth consecutive month SPACs led issuance.
- Across 117 IPOs, $23 billion was raised, implying an average trust size of roughly $200 million, reflecting a more disciplined market than 2021.
- Activity is shifting from IPOs to deal execution. June saw 13 business combinations worth $12.7 billion, lifting live deals to 109 with $71.8 billion in value. Only 22 de-SPACs closed in H1 2026 versus 43 in all of 2025, widening the backlog.
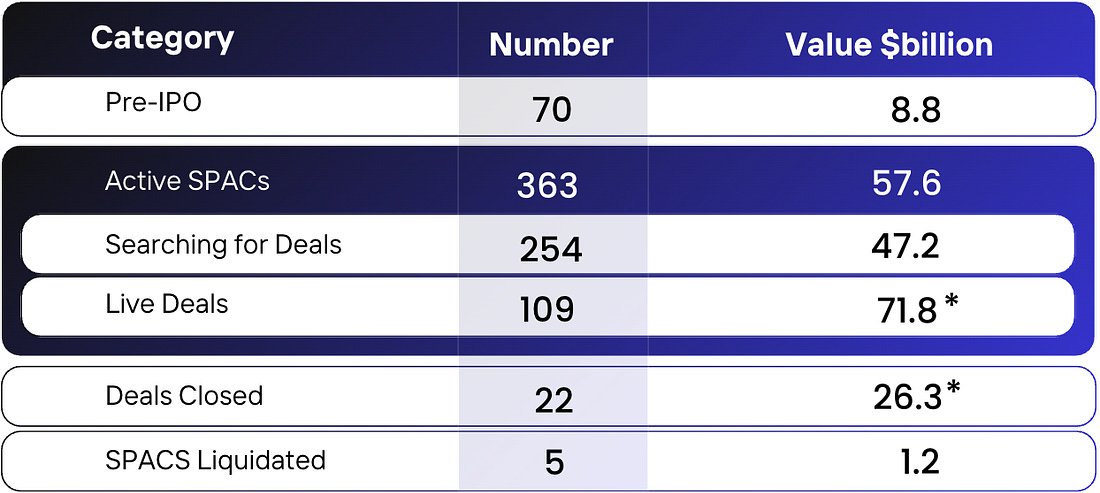
- The acquisition pipeline is at its strongest since 2021, with 254 searching SPACs holding $47.2 billion in trust across 363 active vehicles totaling $57.6 billion.
Fundraising in the USA
Private Markets: Capital Consolidates Into a Structurally Smaller Cycle
- Fundraising remains subdued. Q1 2026 raised $54.2 billion across 84 funds, following $286.0 billion across 406 funds in 2025, the lowest since 2020, versus $377.5 billion in 2024.
- Capital concentration intensified. The top 10 funds captured $34.5 billion, or 63.7% of Q1 2026 fundraising, as LPs favored large multi-strategy platforms over specialist managers.
- Manager participation continues to shrink. 84 Q1 closes annualize well below 2025's 406 and the 1,000-plus seen in 2023, increasing pressure on emerging GPs.
- Scale continues to dominate. Average fund size rose to about $645 million in Q1 2026 from about $521 million in 2024, while record $1.1 trillion of dry powder represents just 29.6% of AUM versus a 10-year average of 35.9%.
Public Markets: Blank-Check Boom Extends Into Mid-Year
- SPACs accounted for 60% of all U.S. IPOs in H1 2026, up sharply from 42% in 2025 and just 19% in 2024, and nearing the 61% peak of 2021.
- Issuance and dealmaking are both firing. June delivered $4.0 billion raised in IPOs, 13 business combinations announced at $12.7 billion of equity value, 7 closings at $6.2 billion, and zero liquidations.
- The pipeline is deep and the aftermarket healthy, headlined by Churchill Capital XI/Agility Robotics and standout post-close performers such as Boost Run and Horizon Quantum.
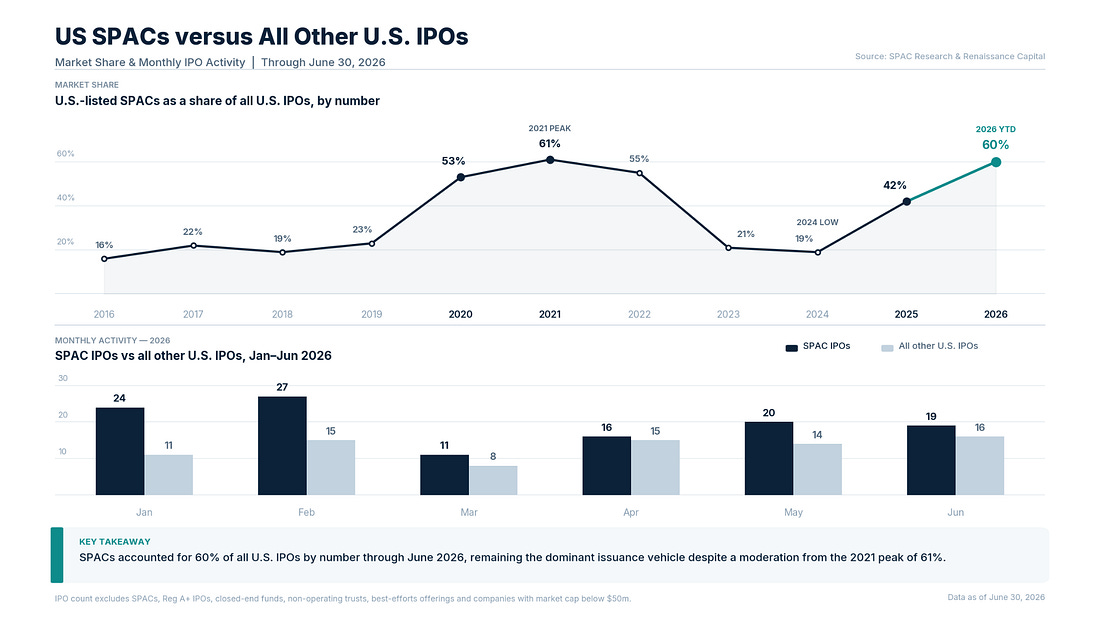
SPAC Issuance Reclaims 60% of the U.S. IPO Market as Trust Capital Nears $58 Billion
- Market share: SPAC issuance is no longer a niche complement to traditional listings, it is once again the dominant route to the U.S. public markets.
- Record capital base: 363 active SPACs hold $57.6 billion in trust, one of the deepest pools of committed acquisition capital assembled since the post-2021 reset.
- Search capital: 254 SPACs holding $47.2 billion remain in search mode, implying intensifying competition for quality targets and pricing power shifting toward sellers.
- Conversion environment: 22 closings for $26.3 billion against only 5 liquidations returning $1.2 billion indicates sponsors are executing rather than winding down.
- Forward pipeline: 70 pre-IPO registrations seeking $8.8 billion, replenished by June's 23 fresh S-1 filings, support elevated issuance through year-end.
| Monthly activity (June 2026) | Number | Value ($bn) |
|---|---|---|
| S-1s filed | 23 | 4.1 |
| IPOs | 19 | 4.0 |
| Deals announced | 13 | 12.7 |
| Deals closed | 7 | 6.2 |
| SPACs liquidated | 0 | 0.0 |
Recent Closed De-SPAC Transactions
| SPAC | Target | Sector | PF EV ($m) | PIPE ($m) | Redemptions |
|---|---|---|---|---|---|
| Welsbach Technology Metals Acq. Corp. | Evolution Metals | Natural Resources | 5,933 | - | 99.0% |
| Crane Harbor Acquisition Corp. | Xanadu Quantum Technologies | Technology | 3,131 | 275 | 88.3% |
| Churchill Capital Corp X | Infleqtion | Technology | 1,800 | 127 | 0.1% |
| Cantor Equity Partners II, Inc. | AIR | Consumer | 1,749 | - | 81.1% |
| Cartesian Growth Corporation III | Factorial | Renewable Energy | 1,500 | 75 | 83.5% |
| Legato Merger Corp. II | Einride | Technology | 1,350 | 113 | 98.5% |
| Inflection Point Acquisition Corp. IV | Merlin | Technology | 1,330 | 213 | 90.2% |
| Mountain Lake Acquisition Corp. | Avalanche Treasury Corporation | Crypto | 1,313 | 28 | 99.7% |
| A Paradise Acquisition Corp. | Enhanced Games | Hospitality | 1,310 | - | 98.1% |
| Vine Hill Capital Investment Corp. | Coinshares | Financial Services | 921 | 50 | 94.2% |
| GigCapital7 Corp. | Hadron Energy | Renewable Energy | 796 | - | 84.2% |
| Haymaker Acquisition Corp. 4 | Suncrete | Manufacturing | 777 | 167 | 56.5% |
| EQV Ventures Acquisition Corp. | Presidio Petroleum | Renewable Energy | 735 | 213 | 96.0% |
| Voyager Acquisition Corp. | VERAXA Biotech | Biotech | 590 | 274 | 99.3% |
| dMY Squared Technology Group, Inc. | Horizon Quantum Holdings | Technology | 546 | 112 | 85.4% |
| Willow Lane Acquisition Corp. | Boost Run | Technology | 502 | - | 0.0% |
| Spring Valley Acquisition Corp. II | Eagle Nuclear Energy | Natural Resources | 312 | 30 | 98.2% |
| Pelican Acquisition Corporation | Greenland Energy Company | Renewable Energy | 260 | - | 87.7% |
| Horizon Space Acquisition II Corp. | SL Bio | Biotech | 253 | 8 | 97.4% |
| Trailblazer Merger Corporation I | Cyabra Strategy | Technology | 106 | 8 | 98.2% |
Heatmap: Growing Sectors and Geographies
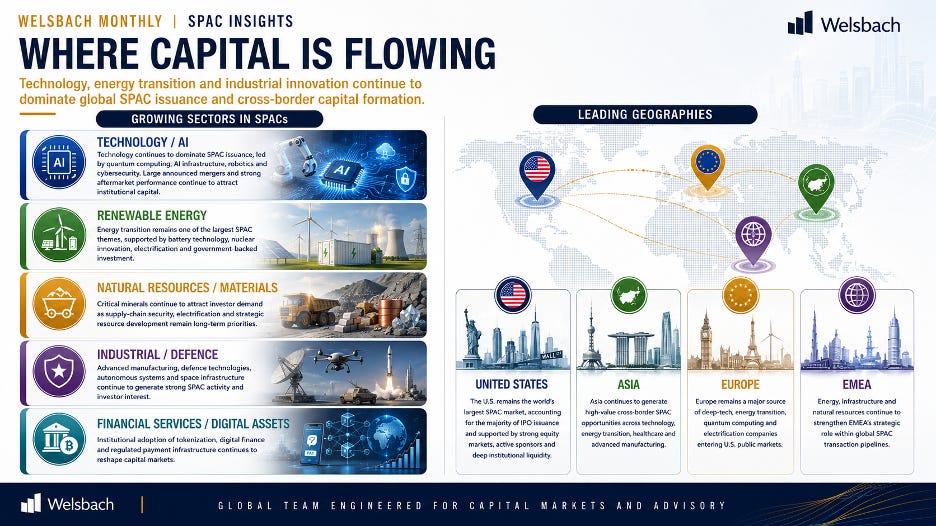
Growing sectors
- Technology and AI: the largest SPAC sector in June, led by EigenQ ($3.0bn), Terra Quantum ($3.6bn), Xanadu ($3.6bn), Agility Robotics ($2.5bn) and Infleqtion ($1.8bn).
- Renewable energy: the largest announced theme, led by ProLogium ($3.8bn), newcleo ($2.4bn) and Zincfive ($752m), with strong trading in Factorial, Presidio Petroleum and GreenRock.
- Natural resources and materials: critical minerals continue to attract capital, led by Evolution Metals' $5.9bn completed de-SPAC, alongside US Elemental, Sio Silica and Eagle Energy Metals.
- Industrial and defence: some of the strongest post-de-SPAC performance, led by Suncrete, with Merlin, Quantum Space, NorthStar Earth & Space and Einride in the pipeline.
- Financial services and digital assets: tokenization and regulated digital finance, led by Securitize ($1.8bn), Teamshares ($926m), Coinshares ($921m) and Openpayd ($881m).
Leading geographies
- United States: SPACs accounted for 60% of all U.S. IPOs YTD, with Q2 delivering 50 SPAC IPOs raising $9.0 billion.
- Asia: the strongest live-deal valuations, led by United Hydrogen ($1.6bn), ProLogium ($3.8bn), Supper App ($813m), Leading Group ($573m) and CUBEBIO ($375m).
- Europe: a leading source of deep-tech and energy transition transactions, highlighted by Terra Quantum, newcleo, ProLogium and Einride.
- EMEA: influence through energy, infrastructure and natural resource themes, with cross-border transactions such as Securitize and Sio Silica.
Conclusion
SPACs now account for 60% of U.S. IPOs year-to-date, with 117 IPOs priced for $23 billion and 70 more on file for $9 billion. The pipeline is the deepest in years: 363 active SPACs hold $57.6 billion in trust, 254 are searching with $47.2 billion, and 109 live deals represent $71.8 billion in equity value.
June delivered 13 announcements worth $12.7 billion, seven closings worth $6.2 billion and zero liquidations, bringing 2026 closings to 22 deals for $26.3 billion. Institutional confidence has improved because deal quality has: multi-billion-dollar enterprise values, committed PIPEs and post-close prices well above trust in quantum, industrials and critical minerals.
For CEOs, founders, sponsors and advisors, the message is unambiguous. The SPAC has re-emerged as a credible, competitive and often faster alternative to the traditional IPO, and execution windows this constructive rarely persist indefinitely.
Download
Take this edition with you
Register once to download this Welsbach Monthly edition as a branded PDF, including all charts and exhibits.